NBFC services to banks will attract 18% GST
The interest on the underlying loan will remain exempt from GST. The 18% levy will apply to the taxable service supplied by the NBFC to the bank in the co-lending arrangement. The committee also decided to align the valuation of the NBFC's service with the methodology prescribed by the Reserve Bank…
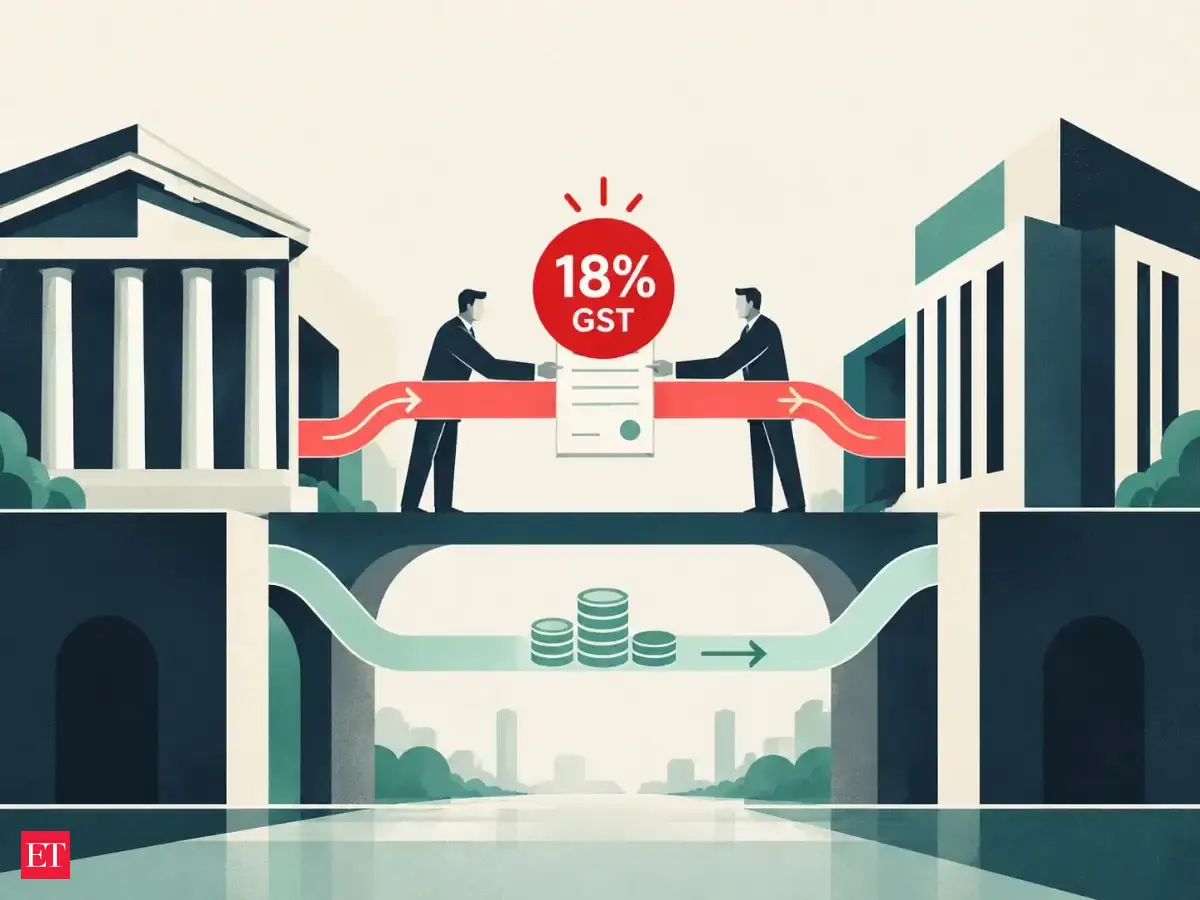
New Delhi: The fitment committee under the Goods and Services Tax (GST) Council has decided that services provided by non-banking finance companies (NBFCs) to banks will be taxable at 18% GST, with their value determined in the manner prescribed by the Reserve Bank of India (RBI), people aware of the development said.The interest on the underlying loan will remain exempt from GST. The 18% levy will apply to the taxable service supplied by the NBFC to the bank in the co-lending arrangement. The committee also decided to align the valuation of the NBFC's service with the methodology prescribed by the Reserve Bank of India.The council has separately proposed that the notional charges recorded when banks transfer funds between their own branches be treated as interest, aligning GST treatment with the substance of the transaction. This provides a regulatory benchmark for determining the taxable component and reduces the scope for different interpretations across co-lending structures. This will make it easier for lenders and fintech platforms to structure partnerships without prolonged disputes over valuation.Also read | New RBI data reveals a recast of India's overnight money market numbers Fitment committee suggested this after proper deliberation with the stakeholders, and a separate circular will be issued if the proposal is cleared by the GST Council, an official told ET on condition of anonymity. The clarification is significant given the litigation and confusion surrounding the taxability of this rapidly expanding lending model. Since co-lending structures involve multiple components - including loan funding, sourcing, credit assessment and servicing- their tax treatment has long been a source of uncertainty for the industry.134772281The industry raised queries last year as to whether an NBFC's income or spread in such arrangements should be treated as interest - which is exempt - or as consideration for a separate service. The council is scheduled to meet on October 8 to discuss the next wave of reforms. Under the co-lending model, the bank and NBFC jointly fund loans, with the NBFC generally bringing its customer acquisition and credit assessment capabilities, while the bank provides a larger share of the financing.Also read | RBI brings new rule for banks to measure risks from derivatives, other such dealingsThe arrangement has been particularly important for extending formal credit to segments where banks have traditionally had limited reach. Currently, the interest from the co-lending business is shared in a predefined ratio. For instance, if a co-lender charges a blended rate of interest of 16% to the customer with the bank entitled to receive 10% on its share, the remaining 6% received from the customer on the bank's share of the loan is retained by the sourcing NBFC. The decision is part of a wider set of measures the government has proposed to the council to resolve long-standing tax ambiguities in the financial services sector and other key sectors, as well as to align GST treatment more closely with the regulatory framework.
Source: ET Banking & Finance
Disclaimer: This article is for general information and does not constitute investment, tax or legal advice. Markets and rates change; please verify with official sources or a qualified professional before you act.